Buy a Home With Zero Down, Zero Cash to Close & Lower Bills
Most homebuyers don't plan for utility bills, down payments, and closing costs. Lowtility covers all three — so you keep your savings and move in for less.

The #1 Mistake Homebuyers Make
When you shop for a home, everyone talks about your mortgage payment — principal, interest, taxes, and insurance (PITI). But nobody mentions the bill that shows up every single month after you move in: your utility bill.
The real cost of owning a home isn’t just PITI. It’s PITI + Utilities.
Electricity, gas, water, and waste can add $200 to $600 per month to your housing costs. That’s money that reduces how much home you can actually afford — and nobody factors it in until it’s too late.
“I could buy today… if I didn’t need the down payment.”
“Closing costs are killing my budget.”
“I don’t want to drain my savings.”
"Affordability stinks."
"I have solar but I'm stuck in a bad loan."
Lowtility was built specifically to solve these problems.
The Real Monthly Cost
Here's what most lenders won't show you — the true cost of owning a home when you factor in utilities.
Which Would You Choose?
What They Got
Conventional
+ Solar
Example based on illustrative scenario. Actual results vary based on qualification, location, interest rate, energy usage, and other factors. PRMI NMLS 3094. Equal Housing Lender.
Stop Renting. Start Owning.
Lowtility bundles your mortgage, down payment assistance, and solar energy into one loan. No second mortgage. No solar lease. No hidden fees.
$0 down, $0 to close
Lowtility DPA covers up to 5% of your purchase price. Keep your savings in your account.
Your house makes its own power
Solar + battery backup rolled into the mortgage. Your utility bill drops to near-zero from day one.
Qualify for more home
No utility bill = more money toward your mortgage. Get the home you actually want, not just what's left over.
One loan. That's it.
No second mortgage, no solar lease, no lien. Everything bundled into a single, simple payment.

What Is Buying Power?
Lenders look at your total monthly cost — not just your mortgage. When your utility bills go down, the home you can afford goes up.

Your monthly budget
What you can spend each month on housing costs
Lowtility cuts your energy
Solar + battery drops your utility bill to near-zero
You qualify for more home
Freed-up money goes toward your mortgage approval
Additional buying power unlocked by eliminating your utility bill — without increasing your monthly payment. Results vary based on qualification, interest rate, and other factors. PRMI NMLS 3094. Equal Housing Lender.
See What Lowtility Looks Like
for Buyers Like You
Two real scenarios showing how Lowtility changes the math on homeownership.

The Garcias

The Johnsons
*Examples are illustrative and based on approximate figures. Actual rates, payments, savings, and eligibility vary based on credit profile, location, loan program, and current market conditions. This is not a commitment to lend. PRMI NMLS 3094. Equal Housing Lender.
What Homeownership Actually Costs
Slide to your home price and see how the numbers compare — mortgage, utilities, cash to close, everything.
Example based on illustrative scenarios. Actual results vary based on qualification, location, interest rate, energy usage, and other factors. PRMI NMLS 3094. Equal Housing Lender.
One Program. Built for You.
Whether you're buying your first home, upgrading your current one, closing more deals, or going solar — Lowtility meets you where you are.

Homebuyers
$0 down, $0 to close, lower bills — and up to 5% in DPA. This is how you stop renting.

Homeowners
Refi with a 5 Day HELOC, add solar, or lower your rate. Make your house work harder for you.

Real Estate Agents
Buyers who qualify for more home buy more listings. Move stale inventory — without cutting price.

Solar Reps
Help homeowners refi old panels or go solar for the first time — financed through the mortgage, not a lease.
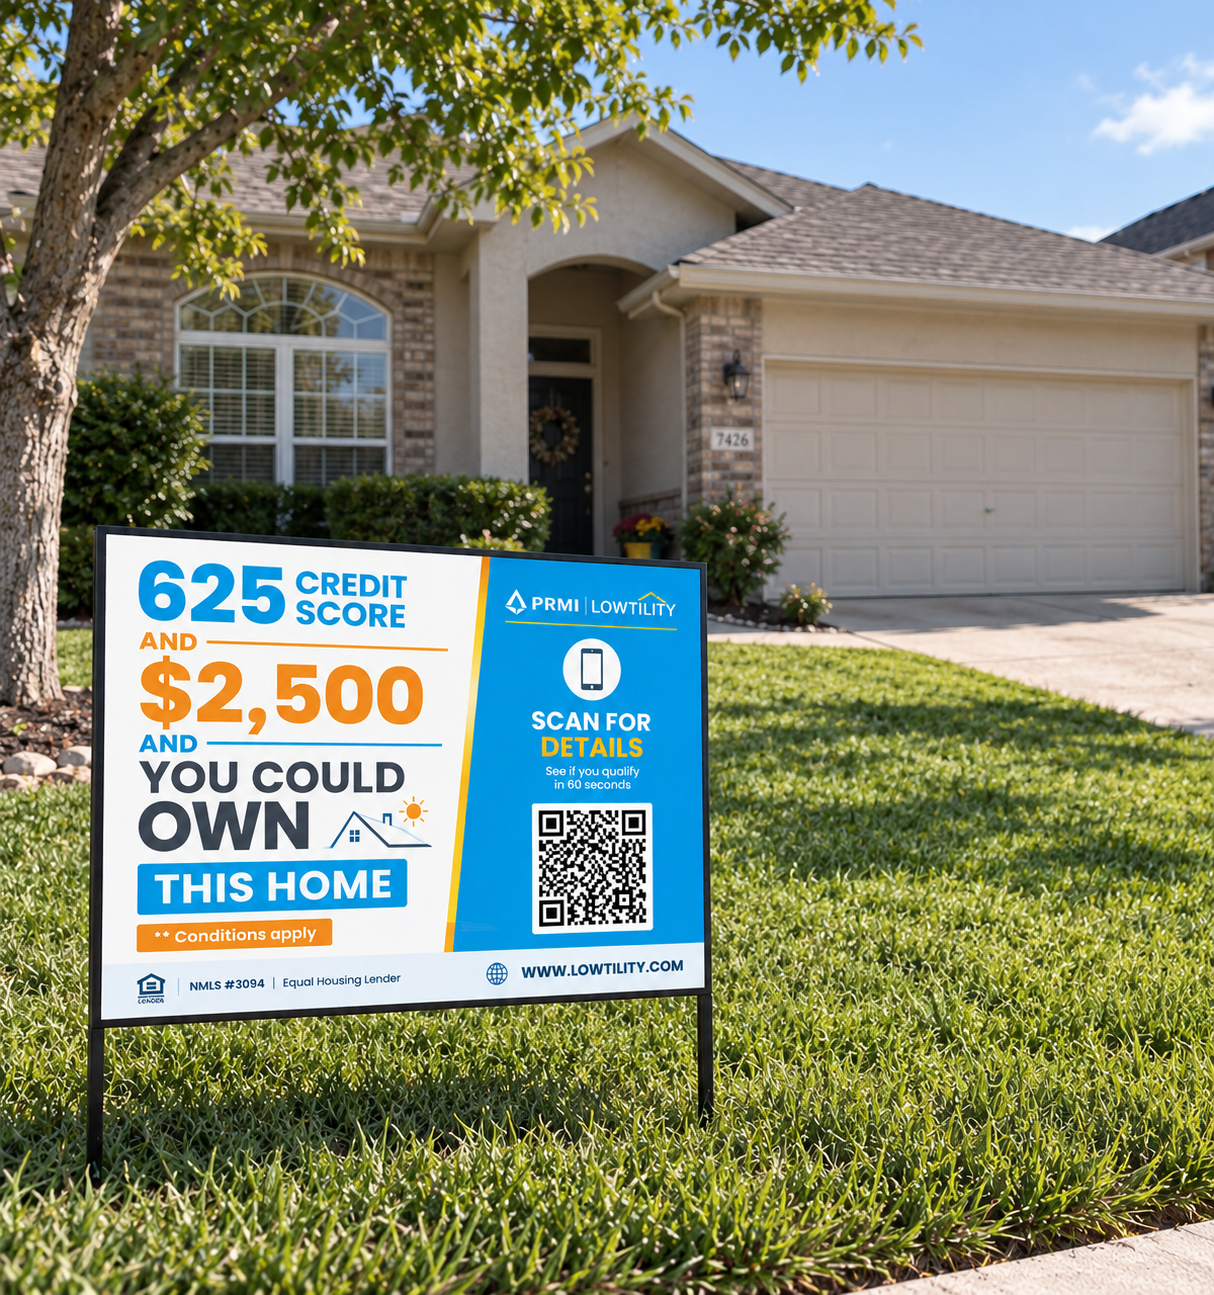
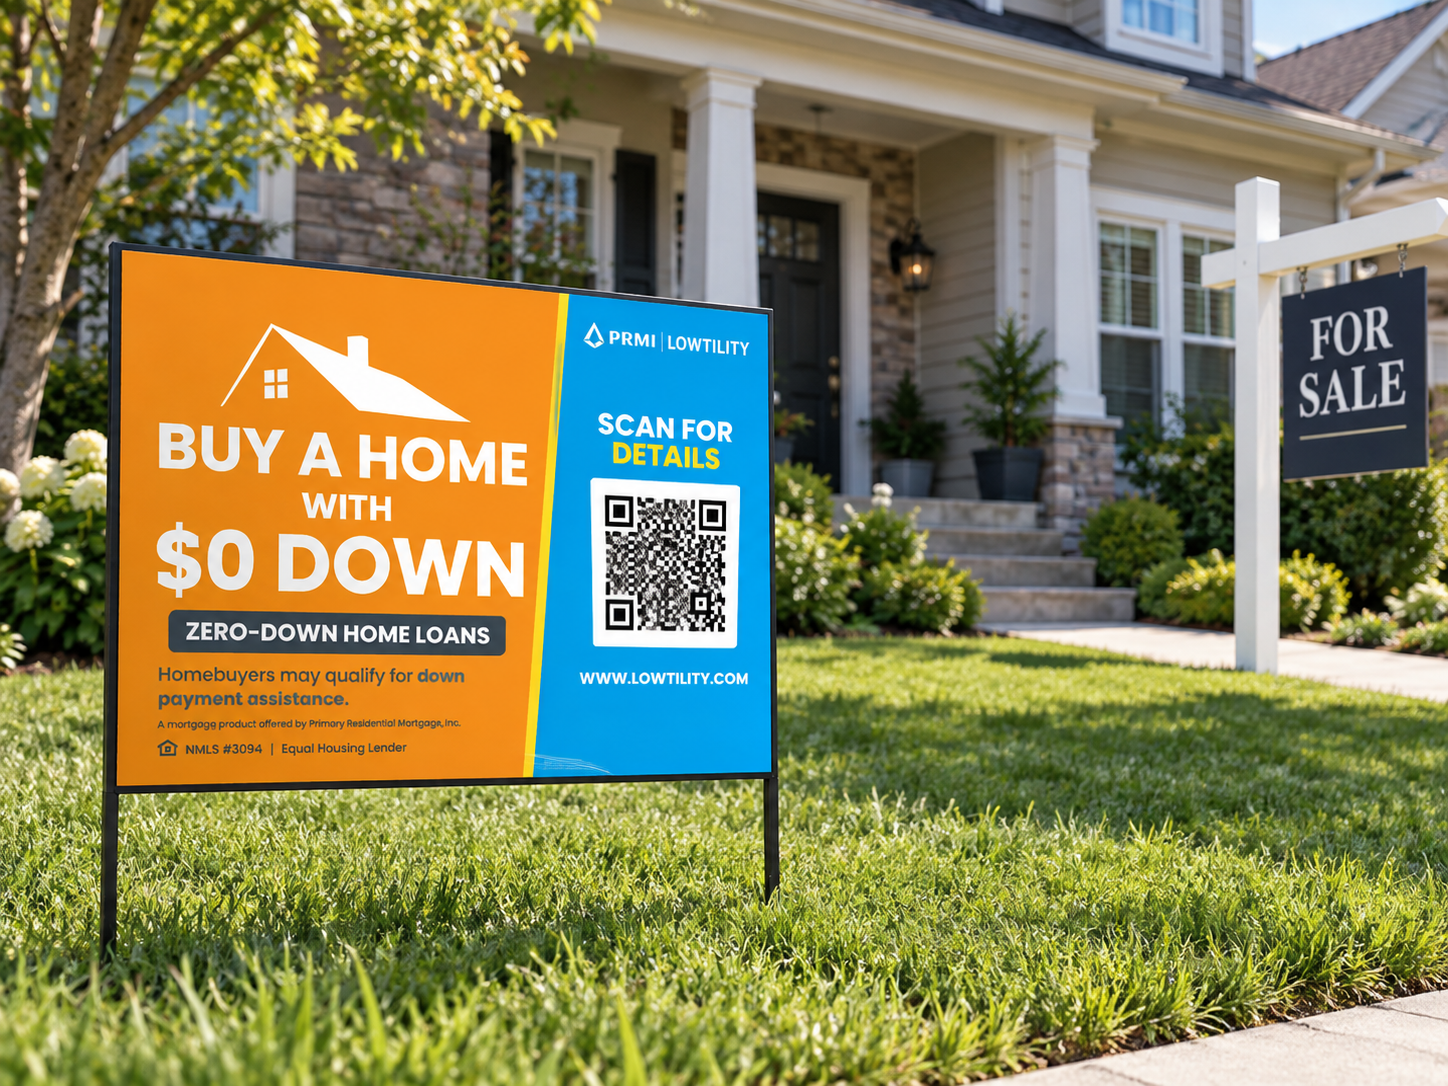
Lowtility homes are already popping up in neighborhoods across the country
625 credit score, $2,500, and you could own a home with solar — yard sign and all.
Three Steps. Zero Surprises.
Get Pre-Approved
Take the quiz or connect with our team. We'll run your real numbers — including DPA, utility savings, and buying power — so you know exactly what you can afford.
Find Your Home
Shop with your agent — anywhere in the country. No income caps, no location limits, no surprises. Just more home for your money.
Close & Start Saving
Solar and energy upgrades get bundled into your loan — $0 out of pocket. You build equity and save on utilities from the day you get the keys.
Check What Applies to You
Most people qualify for more than they think. Check the boxes and see where you stand.
-
I have a 580+ credit score
-
I'm looking to buy a home
-
I want $0 down payment
-
I'd love lower monthly bills
-
I want a home that makes its own power
-
I'd prefer one loan, one payment
What our Customers say
about lowtility
See What our happy customers had to say about their experience.
Where We Lend
Licensed in 49 States Nationwide
Our branch serves 26 states directly. Need a loan somewhere else? We've got you covered through PRMI's nationwide network.
Backed by One of the Largest
Mortgage Lenders in the Country
Lowtility is built by experienced mortgage professionals and powered by PRMI — a nationwide lender with billions in annual originations and dozens of industry awards.


PRMI NMLS 3094. PRMI is an Equal Housing Lender. Credit and collateral are subject to approval. Terms and conditions apply. Programs, rates, terms and conditions are subject to change and are subject to borrower(s) qualification. This is not a commitment to lend.
Quick answers to the questions we hear most.
Everything new buyers want to know about how Lowtility works, who qualifies, and what makes it different.
What exactly is Lowtility?
How is this different from a normal mortgage?
How is zero down payment possible?
What credit score do I need?
Will my monthly payment be higher because of the solar?
Will I own the solar panels?
This sounds too good to be true. What's the catch?
Is this one of those predatory solar loans I've heard about?
What happens when I sell my home?
Can this be done as a refinance?
Ready to See Your Numbers?
When energy costs are designed into the loan, the impact shows up NOW, and grows over time.

MENU
CUSTOMERS
SOCIAL
© 2026 Lowtility. All Rights Reserved.
Lowtility is the name of a suite of mortgage loan programs designed to allow qualified borrowers to make home energy improvements to their home. It is not affiliated with a utility company or a DBA. Primary Residential Mortgage, Inc. NMLS#: 919520 Utah DRE Mortgage Office License # 8335595. MLO 0117736. MC3094-122. All loans subject to credit and property approval. PRMI NMLS 3094. PRMI is an Equal Housing Lender. Some products and services may not be available in all states. Credit and collateral are subject to approval. Terms and conditions apply. This is not a commitment to lend. Programs, rates, terms and conditions are subject to change without notice. 1165 East Wilmington Avenue, Suite 250 Salt Lake City, UT 84106